

Happy Saturday - hope you all are enjoying your weekend so far! First, an update on the flow app that is generating all of these trades: I identified and fixed a few critical performance bugs this morning and it looks to be much improved. I am going to monitor performance this week, and work on building out the alert function (users can determine specific alerts they want). Assuming all goes well with that, going to push it to the server and work on getting it all ready to release. All current paid subs will be locked in for life at my substack’s current pricing ($30/mo) and will get immediate access when it goes live.
Below is the write up for this week’s trade setup flagged by the system + a few other tickers & flow that are catching my eye, let’s dive in!
Ticker: CDNS
Setup Grade: A
Signal fired 07/27/26 · Published 08/08/26
What’s happening
The flow
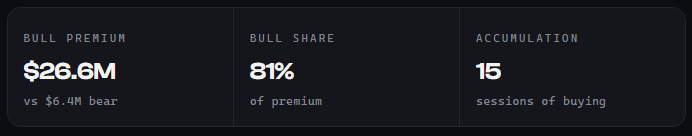
Put-sale-led and heavy: $26.6M bull premium against $6.4M bear, 80.7% dominance across 15 sessions. The anchor is July 17 — 5,002 contracts sold in the Sep $370 puts for $12.29M, struck deep in-the-money (selling intrinsic, an emphatic hold-and-rally bet), plus a floor-walked $250 put sale, $966K, deliberate size. July 21 stacked twenty-plus $340 Nov calls, ~$2.9M total. Crucially, the put-selling continued AFTER earnings (Aug 3-6, $370/$345/$330 lines), so this is real swing accumulation, not just event positioning — though note the July prints were all placed through the report.
The setup
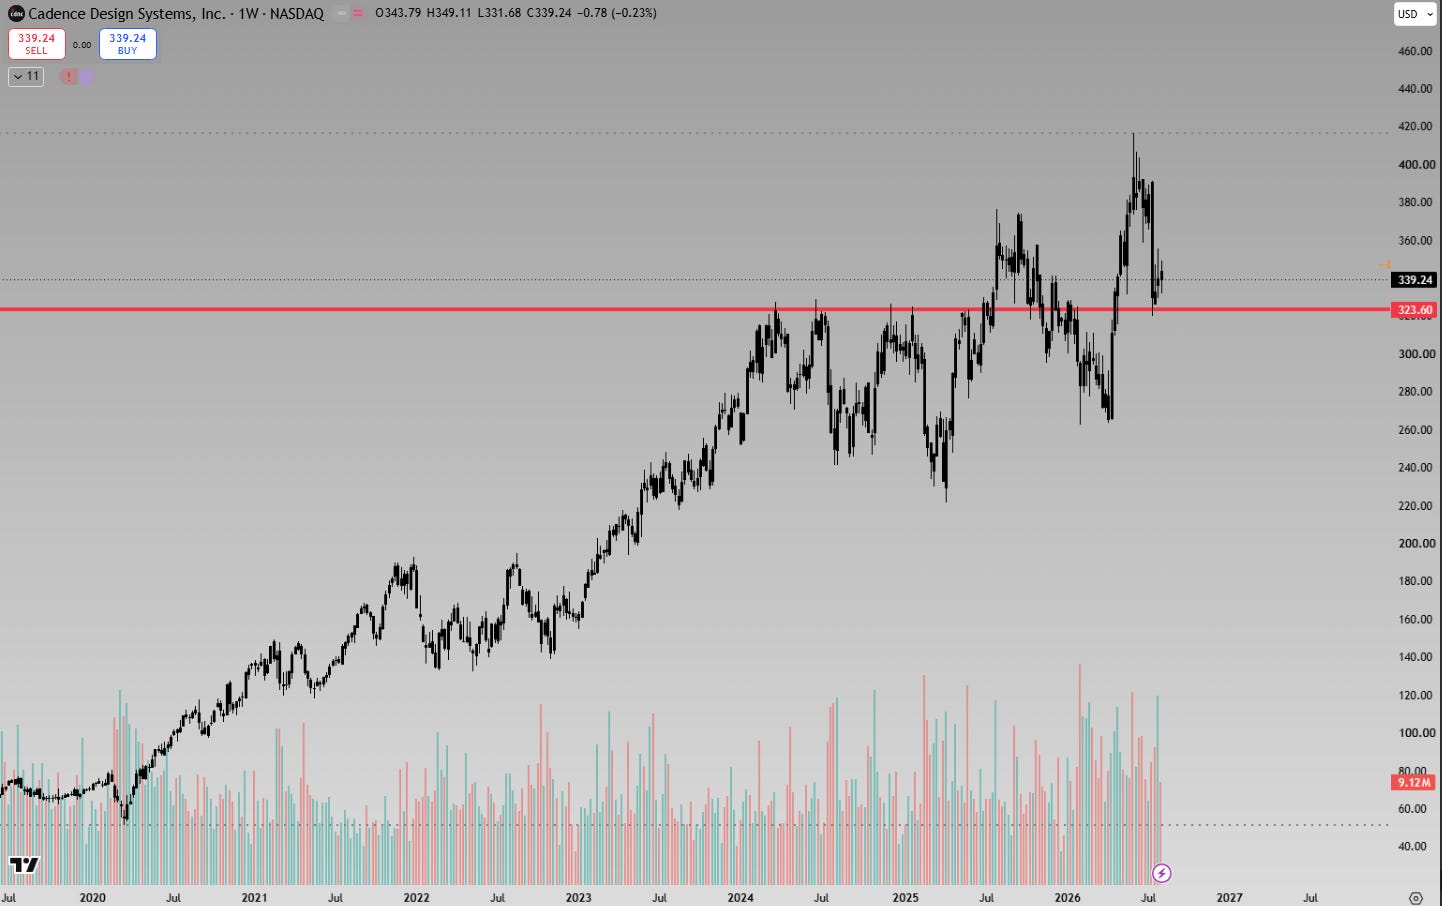
Our buy signal fired 2026-07-27 with CDNS basing near $339. Barely extended since (spot $339). Tape is green, breadth 64%. Institutions have laid a defended floor stack from $300 up to $340.
Invalidation
Thesis is wrong on a daily close below $319.32 — on the short put, that’s your manage/roll trigger, not a panic exit.
Three ways to play it
You choose the structure. All prices are Black-Scholes estimates for sizing — check the chain.
1. Put credit spread $310/290 (defined-risk income)
Legs: SELL $310P 2026-09-18 / BUY $290P 2026-09-18. Est. entry -4.65, cost -$465/contract (credit), max loss $1,535, max gain $465, breakeven $305.35, estimated chance of profit 0.73. Why: same floor, hard-capped risk. Warning: credit is under 1/3 of the width — thin pay for the risk; demand better entry pricing or skip. Exit: close at 50% of credit or 21 days to expiry.
2. Call debit spread $340/370 (directional defined-risk)
Legs: BUY $340C 2026-11-20 / SELL $370C 2026-11-20. Est. entry 11.80, cost $1,180, max loss $1,180, max gain $1,820, breakeven $351.80, estimated chance of profit 0.41. Why: mirrors the institutional call strikes ($340 bought, $370 the next level up). Warning: exit by ~20 sessions; don’t ride the last two weeks of theta. Sell into the first +5-8% move.
3. Risk reversal: sell 3x $310P (2026-09-18) / own $380C (2026-11-20) (convexity)
Legs: SELL 3x $310P 2026-09-18 / BUY 1x $380C 2026-11-20. Est. entry -1.60, net -$160/contract (credit), max loss $92,840, max gain uncapped, breakeven $310.00, estimated chance of profit 0.70. Why: date-skewed — the short 41-day puts decay fast at their floor while you own the same $380 November call the institutions bought, for a ~$160 net credit. Warnings: assignment on 3x puts below $310 — only size what you’d happily own; margin account required. Exit: close short puts at 80% premium capture, ride the calls while the floor holds.
Advanced hands: the bench holds a cash-secured $310 put and the outright $340 November call ($2,933K of premium sat on that line) — more torque, more theta.
Full desk notes
The story
Institutions have been selling downside and buying upside in Cadence for a solid month, and the balance is lopsided: $26.6M in bullish premium against $6.4M bearish, an 80.7% dominance read across 15 bullish sessions. The tell is a wall of put sales at $370 stacked next to persistent call buying at $340 and above — smart money getting paid to underwrite the floor while owning the upside line. Our buy signal fired on 2026-07-27, and the name is sitting right on top of that level: spot $339.24 versus a signal close of $338.61, essentially unmoved, so you are not chasing an extended tape. Context, not thesis: this is a 67.5x trailing / 35.6x forward earnings compounder growing revenue 24.2% with 85.9% gross margins — priced for execution, and the flow is betting execution holds.
The company & the calendar
Cadence builds the AI-driven EDA software, hardware, and silicon IP that chip designers can’t ship without — a toll booth on the semiconductor design cycle. The numbers: 16.0x sales, 23.6% net margins, earnings up 125.4% year over year, and only 2.26% of float short, so this is not a squeeze setup — it’s institutional conviction. Twenty-six analysts rate it strong buy with a target range of $300 low / $403.67 mean / $470 high against a $339 spot; the street’s mean sits 19% above the tape, so coverage is ahead of price, not chasing it. Next earnings land 2026-10-26. The flow rhymes with the news: “Cadence Q2 Earnings Top Estimates on AI Demand, Backlog Hits $8.1B” (Zacks, 2026-07-30) sits mid-window, and the heaviest put-selling day preceded it — quiet accumulation into the print, then confirmation after.
The tape, day by day
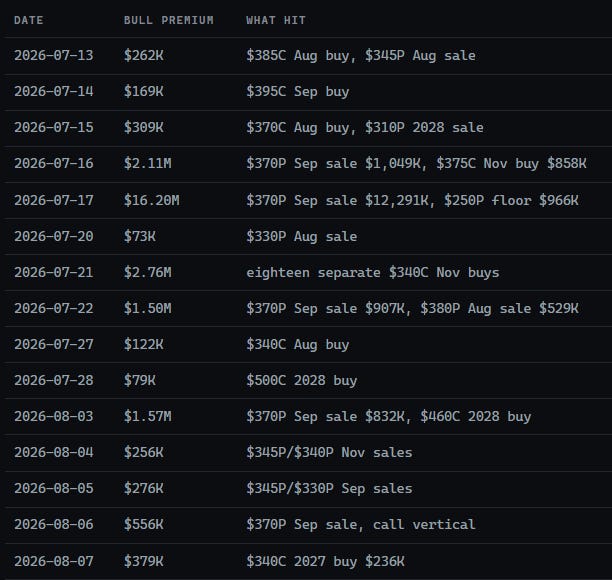
The pattern is repetition, not a one-off. The $370 put line gets sold again and again from July 16 through August 6, and July 21 was eighteen distinct $340 November call buys in one session — one desk methodically building a position.
The receipts
The July 17 monster verified clean: $370P 2026-09-18, 2,739 contracts, $40.5M premium, open interest jumping 21,606 → 34,058 for a +12,452 delta — that is real new positioning, not a roll. The $250P August floor confirmed hard (54 → 3,727 OI). The $375C November buy confirmed (23 → 210), as did the $380P August sale (157 → 220). Not everything held: the July 22 $370P print (200 lots, $907K) showed OI slipping 11,262 → 10,563 — not confirmed — and the August 3 $370P (273 lots, $831K) also failed to add (10,640 → 10,382). The core thesis rests on the confirmed prints, and those are enormous.
The levels
The floor map, ranked by premium underwriting each strike:
$370 — $17.66M sold. The defended line; institutions are paid to defend it.
$250 — $965,925 (deep disaster floor).
$345 — $565,992. $330 — $494,052. $300 — $482,201.
The invalidation is $319.32. Expect a normal shake-out of -6% to -8% off recent levels before any move — that is typical noise inside this floor structure, not thesis failure.
The clock
The September 18 short puts sit in front of the October 26 earnings and decay well before the print — that is the income clock. The November 20 calls carry the directional book through and past earnings, which is where the catalyst lives. Positioning is fresh; the thesis stays live while price holds above the floor and goes stale if the tape drifts sideways below $340 into late September with no follow-through.
A few additional tickers & flow I found that are interesting setups:
BWXT:
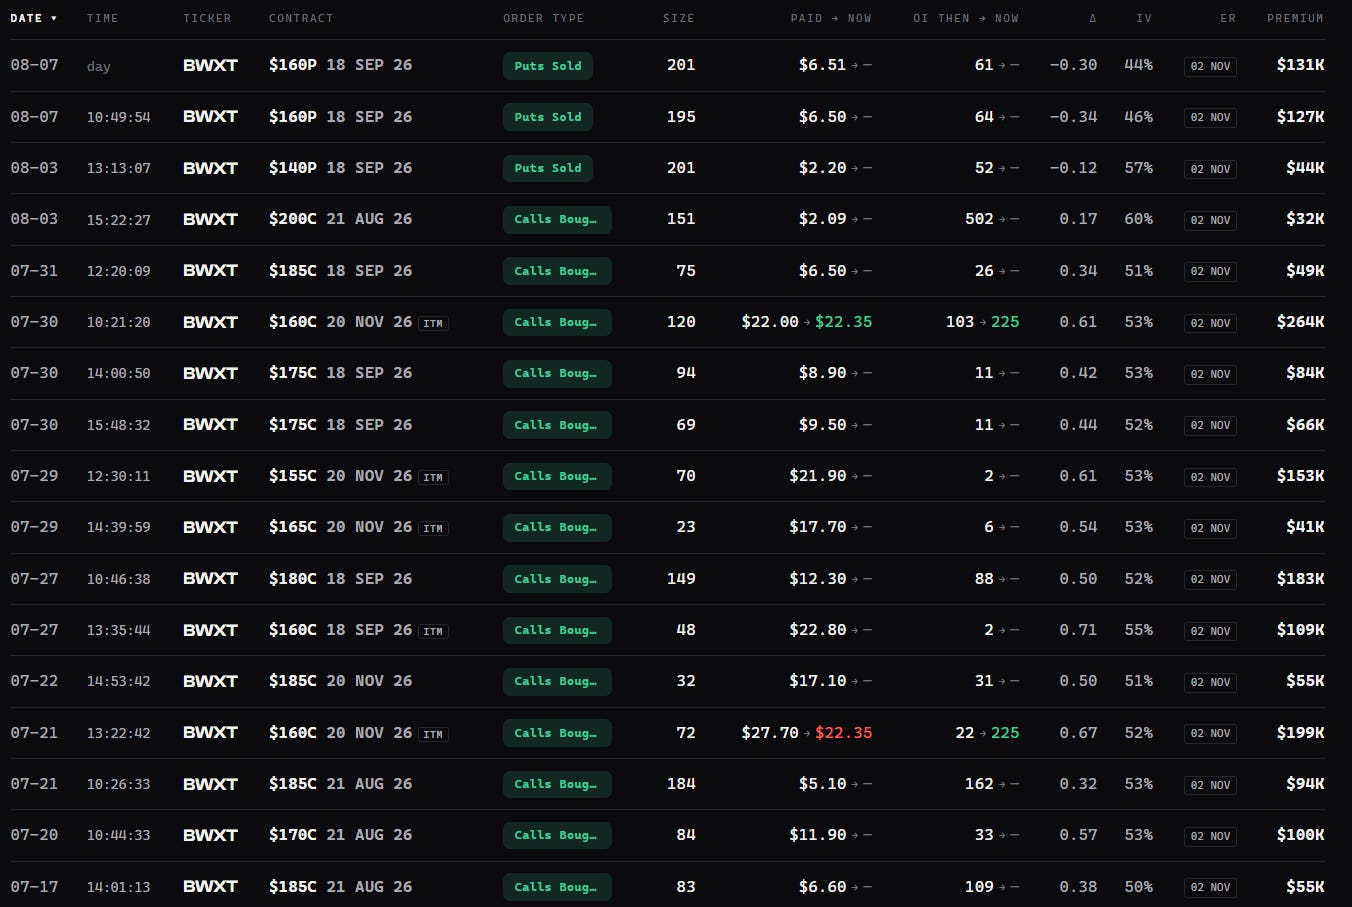
Strong floor established at $160 with players attacking the upside $175 & $185 calls
UBER:
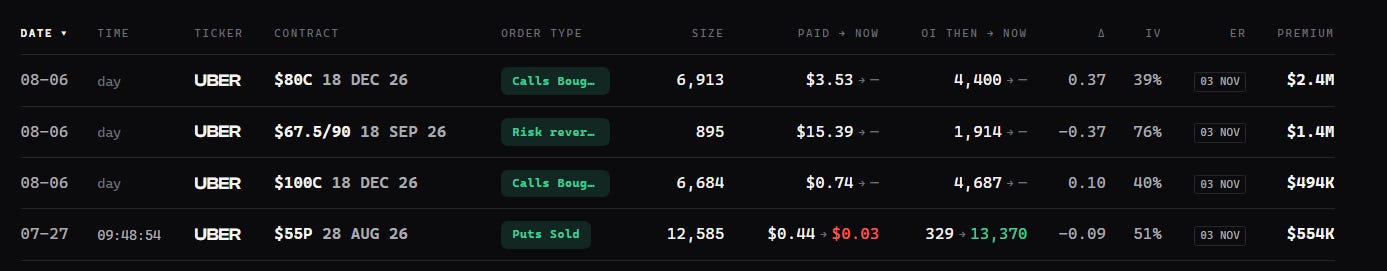
Some size upside December calls hitting the $80 & $100 calls
Large risk reversal on 8/6, selling the September deep ITM $90 puts to buy the ITM $67.5 calls — a massive bullish bet post-earnings.
I’m sure more flow and setups will show up this week so will be active with posting as they flow in on here & Discord. Invite below for those not in the discord yet!
Discord Invite Link -
https://discord.gg/dPTp6qDzAp
Have a great rest of the weekend.